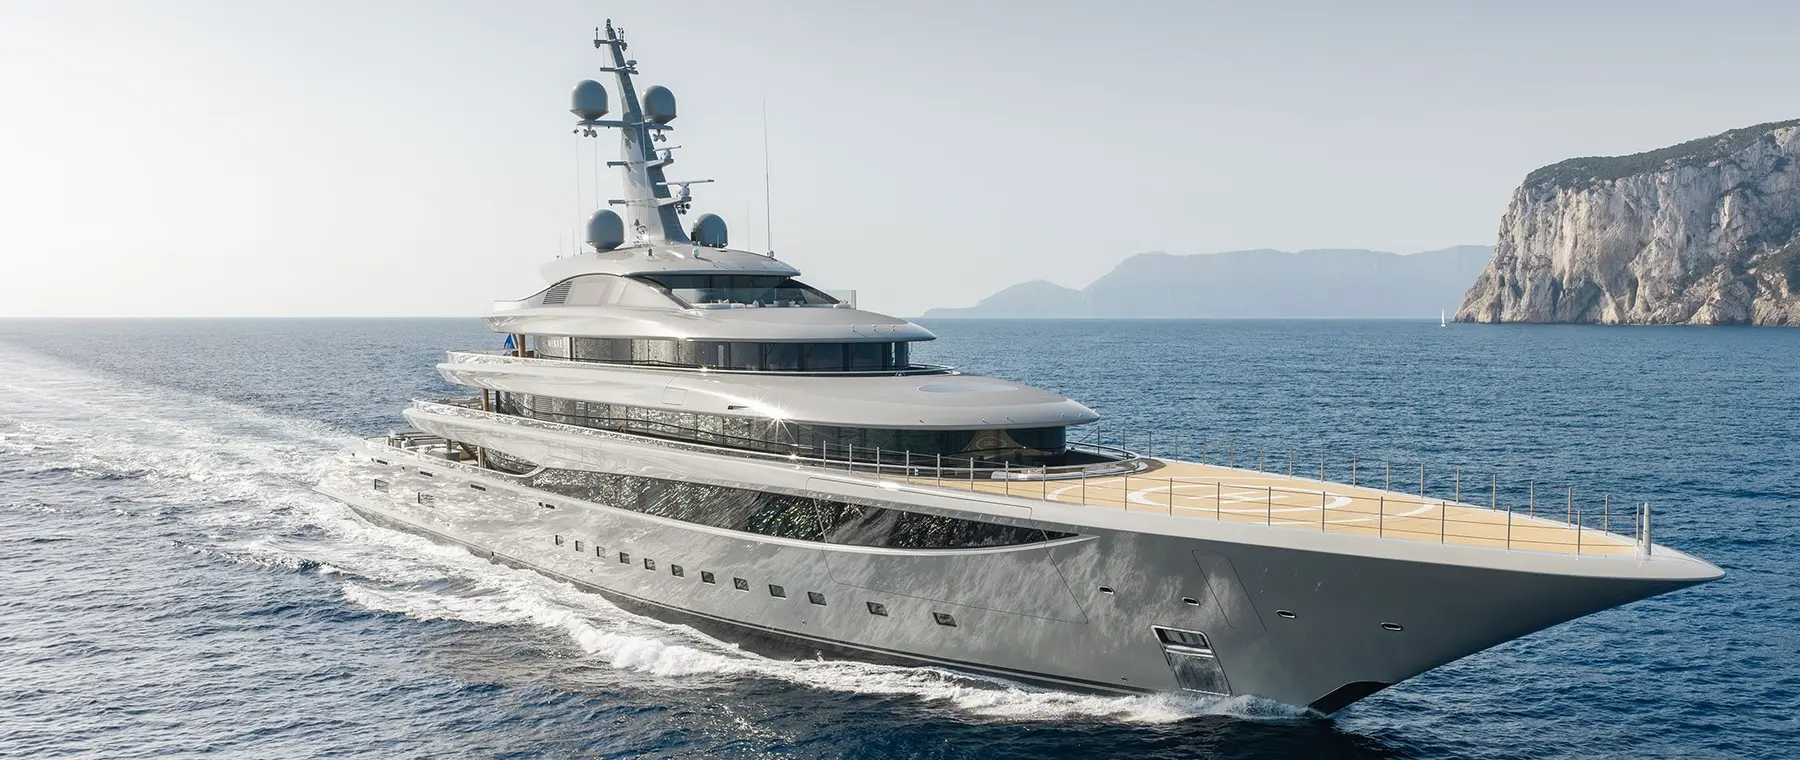
Edmiston sees a divided 2026 yacht market
Edmiston's third-quarter review reports 254 superyacht transactions during the first nine months of 2026, around four per cent fewer than the equivalent period last year. Published on 7 October, the company's analysis describes a relatively resilient market overall but a clear difference between smaller brokerage yachts and those above 40 metres. The figures are a useful signal for owners and buyers, provided they are understood as the broker's stated market dataset rather than a universal count of every private transaction.
The headline decline is modest, yet averages can conceal very different conditions inside a market. A yacht in the 30–40-metre class is purchased for different purposes and at a different price level from a 70-metre custom vessel. Edmiston's central argument is that the transaction pattern in 2026 has not been uniform across those sizes. That distinction matters for anyone deciding when to bring a vessel to market or how aggressively to negotiate on an acquisition.
A strong opening quarter gave way to slower trade
The company says the year began with first-quarter sales running ahead of the same periods in both 2025 and 2024. Activity then softened in the second quarter, which Edmiston identifies as the weakest second quarter since 2020. A modest improvement in August helped the market regain some ground, but not enough to return the first nine months to the preceding year's transaction total.
That sequence suggests timing is important when reading market statistics. An owner who lists a yacht during a quieter period may experience different enquiry levels from one whose vessel reaches buyers around a major yacht show. The data do not prove that a particular month will be better for every boat. They do show why a sales strategy should account for seasonality, competing inventory and the actual quality of buyers rather than rely on a single annual percentage.
The 30–40-metre segment softens
Edmiston attributes much of the overall reduction in transaction numbers to yachts between 30 and 40 metres. It reports sales in that group around 17 per cent below the comparable 2025 period. Because this segment accounts for a substantial share of the market by number of boats sold, a weakness here can depress the total even while the upper-size categories remain active.
Owners in this range should avoid interpreting that percentage as an automatic fall in the value of their own yacht. A count of completed transactions is not the same as a price index, and the composition of boats offered for sale may change. Condition, builder, age, location and realistic asking price still influence the result. A current appraisal should therefore use comparable recent sales and the competing listings relevant to the vessel, not multiply its valuation by a broad market statistic.
Sales above 40 metres tell a different story
The same Edmiston report states that sales activity in the 40-metre-plus segment was almost 20 per cent ahead of the corresponding 2025 period. This contrasts sharply with the weaker 30–40-metre category and is the core finding of the company's Q3 update. It indicates that larger-yacht buyers remained willing to transact in a year when other parts of the market had slowed.
The result does not mean every large yacht was easy to sell. Above 40 metres, each vessel can represent a highly individual combination of pedigree, delivery date, layout and operational capability. Fewer comparable transactions also make an exact valuation more challenging. Nonetheless, a stronger count of concluded deals suggests that well-matched buyers and sellers have been active, and it gives brokers reason to focus on the quality and scarcity of the individual opportunity.
Inventory matters as much as demand
Edmiston reports that the number of newly offered yachts coming to market fell by about 15 per cent year on year. It also describes limited attractive opportunities in the 60–120-metre range, where buyers may face a relatively narrow selection of recently built or exceptionally maintained vessels. When desirable inventory is scarce, a buyer's difficulty may be finding a suitable yacht rather than agreeing that the wider market is active.
Inventory figures should be treated separately from transaction volumes. A market can produce a healthy number of sales while the total number of new listings is shrinking, particularly if existing desirable yachts are being absorbed. That relationship may support stronger negotiating positions for certain sellers, but it is not proof that every asking price is sustainable. The balance depends on how many suitable alternatives a serious buyer can inspect.
Recently delivered yachts attract attention
The Q3 update identifies a 23 per cent year-on-year rise in sales of brokerage yachts less than five years old. That is consistent with the premium many buyers place on modern equipment, contemporary layouts and the prospect of entering service without a long initial refit. It also illustrates how age composition can change the character of a market even when headline transaction counts move only slightly.
Edmiston cites its sale of VIRTUOSITY as an example of a relatively quick transaction, saying the yacht sold in 255 days, less than half the market average reported by the company. One sale should not be treated as a guaranteed benchmark for others. It is better evidence that an individual yacht with attractive characteristics and suitable market positioning can find a buyer faster than the broad average would suggest.
Large transactions are visible and private
Edmiston names the 67-metre Feadship HAMPSHIRE among its recent sales and says it has also handled confidential transactions involving yachts above 75 and 100 metres. Those examples give substance to its description of continued higher-end activity, although the company does not disclose every commercial term. The report also discusses a transaction in which a yacht of more than 75 metres was not openly advertised for sale.
Private arrangements are an important limitation on public-market analysis. Listings and asking prices provide useful information, but some of the largest purchases are negotiated through networks that are not visible in standard online inventories. Owners and buyers therefore need to understand how a broker sources off-market opportunities and verifies the position of the seller. A public listing database alone may not fully describe the options available at the top of the market.
Monaco and new construction add context
The firm's review looks back at the Monaco Yacht Show, where it presented what it called its largest-ever line-up. Among the yachts highlighted were the 102-metre Lürssen NIXIE, 88-metre Turquoise ANGELIQUE and 72-metre Sanlorenzo SILVER FOX, all identified as newly delivered vessels making Monaco appearances. Those names illustrate the connection between large-yacht brokerage, charter promotion and the continued flow of new construction into the market.
Edmiston also referred to the sale of a 57-metre Benetti project still under construction. Such a transaction has a different timetable from the purchase of a yacht already in service, involving design status, contract rights and eventual delivery arrangements. Grouping those activities together under a general discussion of superyacht business is useful, but buyers should distinguish a construction contract from a completed second-hand sale when comparing market evidence.
What the numbers mean for owners
For someone considering a sale, the Q3 review suggests the first step is to identify the relevant comparison group. A 35-metre yacht faces a different headline pattern from one above 50 metres, and a nearly new vessel may draw a different audience from a yacht requiring substantial work. The asking price needs to reflect those realities alongside the owner's desired timing and willingness to accommodate surveys or further negotiations.
Potential purchasers can use the figures to ask sharper questions rather than assume a broad buyer's or seller's market. How many genuinely comparable vessels are offered? Which have sold recently, and after how long? Are there private opportunities outside the published listings? A well-supported acquisition decision also considers service history, refit needs, flag and class documentation, operating expenses and the cost of bringing the vessel to the intended cruising area.
A measured reading of the Q3 evidence
The Edmiston figures describe a year-to-date brokerage picture through September, not a prediction of how the final quarter will close. The company expected major opportunities around the Fort Lauderdale International Boat Show, but that expectation should not be confused with verified full-year outcomes. The market could change with further sales, new listings or economic conditions, and a company's proprietary analysis may differ in scope from another research provider.
The grounded conclusion is nevertheless valuable: transaction volumes were close to 2025 overall, smaller brokerage yachts experienced a notable decline, and larger yachts were selling more actively. The combination of fewer new listings and stronger demand for relatively young vessels adds nuance to those differences. For owners, builders and charter investors, the appropriate response is careful vessel-specific analysis rather than relying on the comforting simplicity of one market-wide percentage.